Financing a Massage Chair vs. Paying Cash: Four Real Scenarios
-
- September 14th, 2026
- 45 views
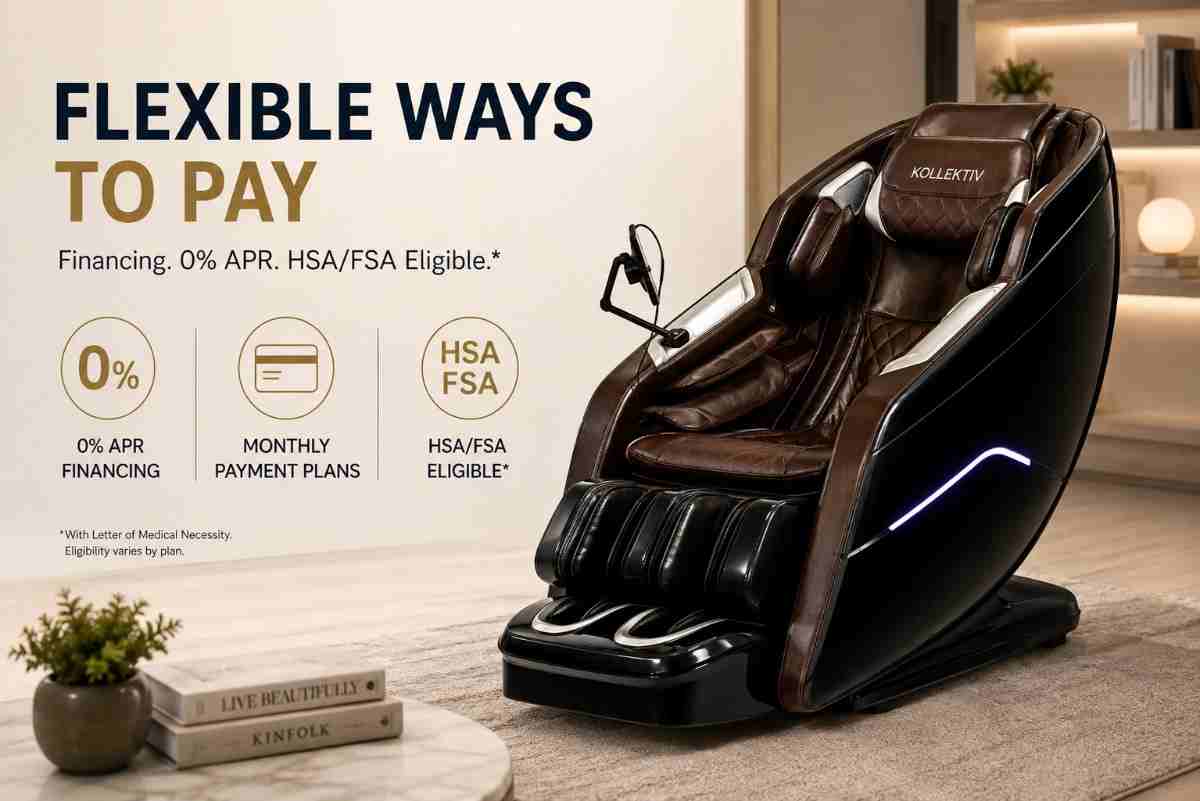
Quick answer: Massage chairs are commonly financed through 0% APR promotional plans or buy-now-pay-later providers at checkout, which spread the cost into fixed monthly payments. Separately, a massage chair is not automatically HSA or FSA eligible – it only qualifies when a licensed healthcare provider documents that it’s medically necessary for a specific diagnosed condition, typically through a Letter of Medical Necessity (LMN). General relaxation or wellness use does not qualify on its own. The rest of this guide breaks down both paths so you can figure out which one, if either, actually applies to you.
Most people default to whichever payment option shows up first at checkout, without actually working through whether it fits their specific situation. Financing isn't automatically the smart move, and paying in full isn't automatically the safe one — which option makes sense depends heavily on your specific numbers and timeline. Our A Buyer's Guide (2026) covers how 0% APR plans and HSA/FSA eligibility actually work mechanically. This piece walks through four common buyer scenarios and which payment path tends to make the most sense in each.
Scenario 1: You Have the Cash, But It Would Drain Your Emergency Fund
Having enough saved to pay for a chair outright doesn't automatically mean paying in full is the right call. If covering an $8,999 flagship chair in one payment would leave your emergency fund thin, financing through a genuine 0% APR plan — not a deferred-interest one — lets you keep that cushion intact while spreading the cost over a fixed period at no additional cost, as long as every payment lands on time.
The math that matters here: If the financing is truly interest-free, there's no financial cost to choosing it over paying cash — the only cost is the discipline required to make every payment on schedule. If your emergency fund would take months to rebuild after a lump-sum payment, that's a reasonable trade-off to make in financing's favor.
Scenario 2: You Have the Cash and a Fully Funded Emergency Fund
If paying in full genuinely doesn't touch anything else in your finances, this is the simplest scenario — paying outright eliminates any risk of a deferred-interest structure catching you off guard, removes the need to track a payoff deadline, and closes out the purchase completely rather than leaving a recurring line item on a monthly budget.
The math that matters here: With a true 0% APR offer, there's no financial upside to paying cash over financing — both cost the same in total. The advantage of paying cash in this scenario is purely about simplicity and removing any tracking burden, not about saving money.
Scenario 3: You're Weighing an HSA/FSA Claim Against a Hard Deadline
If you have FSA funds expiring at year-end and you're hoping a massage chair might qualify, timeline is the deciding factor, not the eligibility question itself. Getting a Letter of Medical Necessity involves scheduling time with a licensed provider, getting the documentation written correctly, and then submitting it to a plan administrator who may take additional time to review it — a process that can easily outlast a hard "use it or lose it" deadline.
The realistic path here: Start the provider conversation as early as possible if this is genuinely worth pursuing, but don't structure your purchase timeline entirely around an LMN coming through in time. If the deadline is close and the medical documentation process hasn't started yet, financing the purchase directly is the more dependable path, with HSA/FSA reimbursement pursued afterward if it clears in time, rather than delaying the purchase itself while waiting on paperwork.
Scenario 4: You Have a Diagnosed Condition Your Provider Already Discusses
If you're already being treated for a condition like chronic lower back pain or sciatica, and massage therapy has come up in conversation with your provider, you're in a genuinely stronger position than someone starting from scratch. Asking directly whether an LMN is appropriate for your specific case is worth doing before assuming you'll need to finance the full amount out of pocket.
The realistic path here: Even in this scenario, financing and HSA/FSA reimbursement aren't mutually exclusive — you can finance the purchase through a 0% APR plan while pursuing reimbursement through your HSA/FSA account separately, using the reimbursed funds to pay down the financed balance faster once it comes through, rather than treating the two paths as an either/or decision.
A Simple Framework for Picking Your Path
| Your Situation | Most Realistic Option |
|---|---|
| Cash available, but it would thin your emergency fund | True 0% APR financing |
| Cash available and finances otherwise fully cushioned | Pay in full for simplicity |
| FSA deadline is close, LMN process hasn't started | Finance now, pursue reimbursement if it clears in time |
| Diagnosed condition, provider already engaged | Explore LMN and financing together, not as competing options |
The One Mistake That Applies Across All Four Scenarios
Regardless of which path fits your situation, the most expensive mistake is treating a deferred-interest offer as if it were true 0% APR. Missing a payoff deadline on a deferred-interest plan means interest gets applied retroactively to the entire original balance, not just what's remaining — a detail that can turn a seemingly interest-free purchase into one costing meaningfully more than the sticker price. Before choosing financing in any of the four scenarios above, confirming the specific terms is worth the extra five minutes it takes.
FAQ
Should I pay cash for a massage chair if I have the money available? It depends on whether paying in full would meaningfully reduce your financial cushion elsewhere. If a true 0% APR plan is available, there's no financial cost to financing instead — the decision comes down to whether you'd rather preserve cash reserves or eliminate the purchase from your monthly budget entirely.
Can I pursue HSA/FSA reimbursement and financing at the same time? Often yes, depending on your specific lender and plan administrator. Financing the purchase while separately pursuing reimbursement, then using reimbursed funds to pay down the balance faster, is a reasonable approach rather than treating the two as mutually exclusive.
What should I do if my FSA deadline is close but I haven't started the medical necessity process? Start the provider conversation as soon as possible if it's genuinely worth pursuing, but don't delay the purchase itself while waiting on paperwork that may not clear in time. Financing directly is generally the more dependable path under a tight deadline.
Is financing ever the better financial choice over paying cash? With a true 0% APR offer, financing and paying cash cost the same in total. Financing becomes the practically better choice when paying in full would meaningfully strain your finances elsewhere, since there's no financial penalty for choosing to spread the payments.
What's the biggest risk across all these financing scenarios? Mistaking a deferred-interest offer for a true 0% APR plan. Missing the payoff deadline on a deferred-interest structure applies interest retroactively to the entire original balance, which can significantly increase the total cost compared to what the monthly payment implied.
Final Thoughts
There's no single correct payment method for a massage chair purchase — the right choice depends on your emergency fund, your timeline, and whether a genuine medical condition is part of the picture. For the full breakdown of how 0% APR financing and HSA/FSA eligibility actually work, our A Buyer's Guide (2026) covers the mechanics in detail — pairing that with an honest look at which of these four scenarios matches your situation is what actually determines the smartest way to pay.