Spoofing in Futures Markets: What Order-Book Records Could Help Expose a Market Manipulation Scheme?
-
- Published Updated
- 106 views
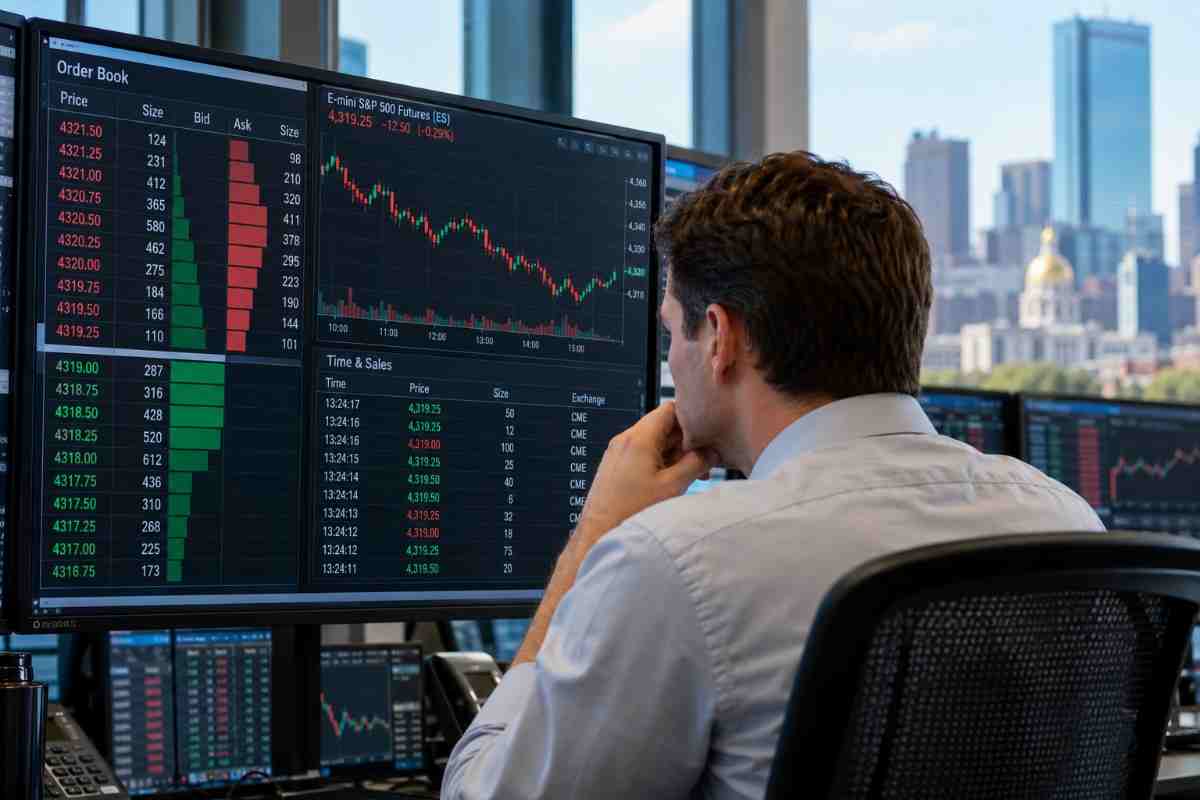
Futures markets depend on accurate information about buying and selling activity. When traders deliberately place orders they never intend to execute, they can create misleading signals about supply, demand, and market prices. This practice, known as spoofing, can undermine market integrity and harm legitimate investors.
Employees who identify suspicious trading patterns may have information that regulators need. Consulting experienced CFTC Whistleblower lawyers Massachusetts can help individuals understand how order-book records may support a market manipulation report and what protections may apply.
What Is Spoofing in Futures Markets?
Spoofing occurs when a trader places a bid or offer with the intent to cancel it before execution. This practice is prohibited under Section 4c(a)(5)(C) of the Commodity Exchange Act.
For example, a trader might place several large buy orders to create the appearance of significant demand. Other market participants may respond by adjusting their orders or prices. Meanwhile, the trader executes a genuine sell order and cancels the misleading buy orders.
The key distinction is intent. Legitimate traders routinely cancel orders because market conditions change. A spoofing violation requires evidence that an order was entered with the intention of canceling it before execution.
Which Order-Book Records Could Reveal Spoofing?
Order-book data can help investigators reconstruct trading behavior and identify potentially deceptive activity.
1. Order Entry and Cancellation Timestamps
Precise timestamps help establish when orders were submitted, modified, executed, or canceled.
Investigators may look for patterns involving:
Large orders canceled shortly after submission.
Repeated cancellations immediately before potential execution.
Genuine trades completed just before opposing orders disappear.
Similar sequences occurring across multiple trading sessions.
These records can reveal whether cancellations consistently coincide with profitable executions elsewhere in the order book.
2. Order Size and Market Depth
Market depth shows the quantity of buy and sell orders available at different prices.
A suspicious trader might repeatedly introduce unusually large orders on one side of the market while maintaining smaller, genuine orders on the opposite side.
Investigators can compare displayed order sizes, available liquidity, and subsequent cancellations to determine whether activity created a misleading impression of market demand.
3. Execution and Fill Records
Execution records distinguish orders that resulted in actual trades from those that were canceled.
Useful evidence may include order identifiers, execution prices, filled quantities, account information, and corresponding cancellation events.
A repeated connection between executed orders on one side and canceled orders on the other may warrant closer examination.
4. Trader Identifiers and Algorithmic Logs
Trader identification records and automated trading logs can help connect suspicious activity to particular accounts, strategies, or trading systems.
The CFTC specifically encourages spoofing whistleblowers to identify relevant markets, contracts, precise timestamps, and Tag 50 identifiers when available.
whistleblower.gov
Algorithmic configuration records and internal communications may also help investigators assess whether cancellations were intentional rather than ordinary risk management.
How Do Investigators Distinguish Spoofing From Legitimate Trading?
High cancellation rates alone do not establish illegal manipulation.
Market makers and other participants frequently modify orders to manage exposure, respond to price changes, or maintain competitive quotes.
Regulators examine the broader trading context, including the relationship between order placement, cancellation, market movement, and actual execution.
Potential warning signs include repeated layering of large orders at several price levels, cancellations after opposite-side trades execute, and internal communications describing an intention to create artificial market interest.
Even then, the evidence must be evaluated carefully. A suspicious pattern does not automatically establish a violation.
Real-World Example: Spoofing in Crude Oil Futures
In September 2023, the CFTC announced an enforcement action involving spoofing in West Texas Intermediate crude oil futures.
According to the agency, the trader placed iceberg orders intended for execution on one side of the market while entering larger, fully displayed orders on the opposite side that were intended to be canceled.
After the genuine orders received fills, the trader canceled the displayed orders. The CFTC described a recurring pattern designed to create a false impression of buying or selling interest.
The case illustrates how order sequencing, visible market depth, and execution records can help reveal deceptive trading practices.
How Can Massachusetts Employees Report Suspected Spoofing?
Employees at trading firms, financial institutions, compliance departments, and technology providers may encounter records suggesting improper futures trading.
Individuals in Massachusetts can submit information involving potential violations of U.S. commodities laws to the CFTC.
An effective report should identify the relevant futures contracts, trading dates, participants, suspicious order sequences, and available supporting evidence.
The CFTC accepts whistleblower information through Form TCR, its official Tip, Complaint, or Referral submission process.
Before collecting or sharing company information, employees should consider confidentiality obligations, legal privilege, and applicable restrictions on accessing records. A whistleblower attorney can help determine what information may lawfully be disclosed.
What Protections and Rewards Are Available to CFTC Whistleblowers?
The CFTC Whistleblower Program provides confidentiality safeguards and anti-retaliation protections for qualifying whistleblowers.
Individuals may submit tips anonymously, subject to specific requirements.
Eligible whistleblowers who voluntarily provide original information leading to successful enforcement actions may receive awards ranging from 10% to 30% of collected monetary sanctions. Generally, the qualifying enforcement action must involve sanctions exceeding $1 million.
Awards are not automatic, and eligibility depends on satisfying program requirements.
Why Work With CFTC Whistleblower Lawyers in Massachusetts?
Reporting sophisticated futures market manipulation can involve complex trading records, confidential information, and potential employment consequences.
Experienced CFTC whistleblower lawyers can evaluate suspicious activity, assess supporting evidence, explain reporting procedures, and help individuals understand their legal rights.
Legal guidance may be especially valuable when the suspected misconduct involves proprietary algorithms, internal compliance concerns, or multiple trading accounts.
Conclusion: Order-Book Evidence Can Help Expose Market Manipulation
Spoofing can distort futures markets by creating artificial signals of supply and demand. Order-entry timestamps, cancellation records, execution histories, and trading-system logs may provide important evidence of these practices.
Employees who recognize suspicious patterns can play an important role in identifying potential violations.
If you have information about suspected futures market manipulation, contact Whistleblower Partners LLP. Its commodities fraud attorneys can help you evaluate your concerns, understand your reporting options, and consider appropriate next steps.
View Whistleblower Partners LLP on Google Maps